Seller Concessions — Day 6: How Much Cash Do You REALLY Need to Buy a House?
Before deciding to buy or wait, let's review your monthly payment, cash to close, emergency savings, home price, and available seller concessions. If the numbers don't work, we wait. I'd rather help you make a smart financial decision than stretch your budget beyond what's comfortable.
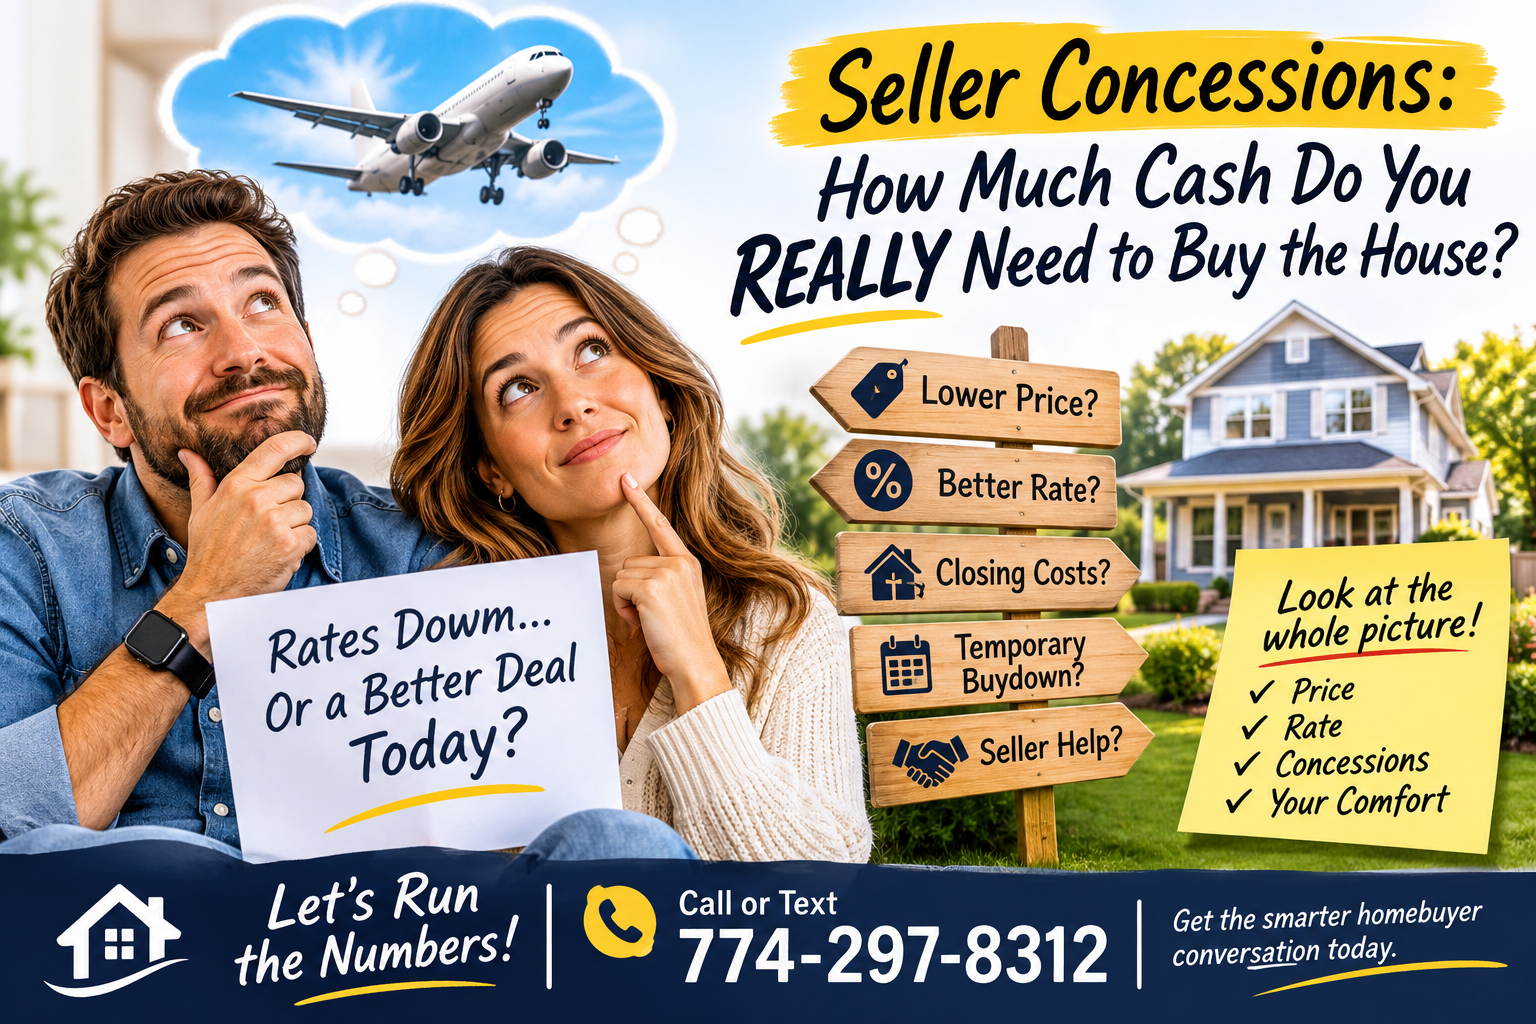
**Don't Wait for the "Perfect" Mortgage Rate!**
**What if waiting for lower mortgage rates causes you to miss a better deal today?**
I hear this all the time: *"I'm waiting for mortgage rates to drop before I buy."*
I get it! Lower rates can mean smaller monthly payments. But here's the catch.
When mortgage rates fall, more buyers may enter the market. That can mean stronger competition, higher offers, and fewer opportunities to negotiate.
Instead of asking, **"When will rates be perfect?"** ask, **"Can we make today's numbers work for me?"**
### Think About Buying an Airline Ticket
Imagine you're flying to Florida. Today's ticket costs $450, but you're waiting for it to drop to $350.
Next week, the plane starts filling up. Suddenly, that same ticket costs $550!
**You focused on the ticket price but overlooked demand.**
Buying a home works similarly. Interest rates matter, but so do the purchase price, seller motivation, competition, concessions, and monthly payment.
**The best deal isn't always the lowest interest rate. It's the deal that works for your budget.**
### How Much Cash Do You Actually Need?
Buying a home involves three important numbers:
- **Down payment:** Your upfront contribution toward the purchase price. - **Closing costs:** Expenses such as lender fees, appraisal, title services, and prepaid taxes or insurance. - **Cash to close:** The amount you actually bring to closing after accounting for your down payment, closing costs, deposits, and eligible credits.
Here's where seller concessions can make a difference.
Suppose you're interested in a **$650,000 home** that's been sitting on the market for several weeks.
Instead of walking away because the payment feels high, what if the seller offered $10,000 in concessions?
Depending on your loan program, that assistance might cover eligible closing costs or help fund an approved interest-rate buydown.
That could reduce the cash you need at closing or provide payment relief.
**But we won't know which strategy works best until we run the numbers!**
### What Happens If Rates Drop Later?
Lower rates sound wonderful. But imagine ten buyers who were waiting suddenly decide to start shopping.
More showings. Multiple offers. Less negotiating room.
A seller who might have helped with closing costs yesterday could receive a full-price offer tomorrow.
Will that always happen? Absolutely not!
But waiting for the perfect combination of low rates and low prices can be like waiting for airline tickets to be cheap during Christmas. Good luck!
And remember, rates can also rise.
### Could a Temporary Rate Buydown Help?
An eligible **1-0 temporary buydown** may lower your effective mortgage payment rate by one percentage point during the first year.
For example, if your fixed note rate is 6.5%, the first-year payment may be calculated using an effective rate of 5.5%, with buydown funds covering the difference.
Beginning in year two, the payment returns to the amount based on the full 6.5% note rate.
**Important:** A temporary buydown doesn't permanently reduce your interest rate. You must qualify for and be comfortable with the full payment.
### Same $10,000. Three Different Buyers.
Imagine the seller is willing to provide $10,000 in negotiating value. How should you use it?
**Buyer A: Wants long-term savings.**
A lower purchase price or permanent rate reduction might make sense.
**Buyer B: Wants to keep more savings.**
Seller assistance toward eligible closing costs could reduce cash needed at closing.
**Buyer C: Wants first-year payment relief.**
An eligible temporary buydown might provide breathing room.
Same house. Same seller. Same negotiating value.
**Three different strategies!**
Remember, a seller price reduction and seller-paid concessions are not interchangeable. Each has different financing effects, and program limits apply.
### Here's My Advice: Shop for Comfort, Not Just Rates!
Before deciding to buy or wait, let's review your monthly payment, cash to close, emergency savings, home price, and available seller concessions.
If the numbers don't work, we wait.
I'd rather help you make a smart financial decision than stretch your budget beyond what's comfortable.
But if seller assistance makes homeownership achievable today, you deserve to explore that opportunity.
**The goal isn't simply to buy a house. It's to buy a home you can comfortably afford.**
### Let's Run the Numbers!
Found a home you love but unsure about the mortgage payment or cash needed to close?
**Send me the purchase price. We'll compare your financing options, potential seller concessions, and estimated cash to close.**
No pressure. No guessing. Just real numbers to help you decide.
**Call or text: 774-297-8312**
*Mortgage rates and pricing can change without notice. Seller concessions, temporary buydowns, discount points, and closing-cost assistance are subject to seller agreement, loan-program limits, available pricing, underwriting requirements, and borrower/property eligibility. Temporary buydowns do not change the underlying note rate. Examples are hypothetical, for educational purposes only, and are not a commitment to lend.*
Frequently asked questions
- Should I wait until mortgage rates drop before buying?
- Maybe, but don't wait so long that the house you love gets ten new admirers! Compare today's rates, prices, and seller concessions before deciding.
- Can a seller really help pay my closing costs?
- Absolutely, if the seller agrees and your loan program allows it! Think of it as getting help with the bill, not a free house.
- Is a 1-0 buydown a permanent mortgage rate discount?
- Nope! It's like a first-year welcome gift—your payment is temporarily reduced, but the full-rate payment returns in year two.
- How much money do I REALLY need to buy a house?
- Maybe less than you think, but your down payment, closing costs, and available assistance determine the answer. Call or text 774-297-8312, and let's run your numbers before you rule yourself out! # Seller Concessions ## How Much Cash Do You REALLY Need to Buy a House?
This article is for informational purposes and is not an offer to lend or a commitment to make a loan. All loans subject to underwriting approval, program guidelines, and appraisal. Equal Housing Opportunity.